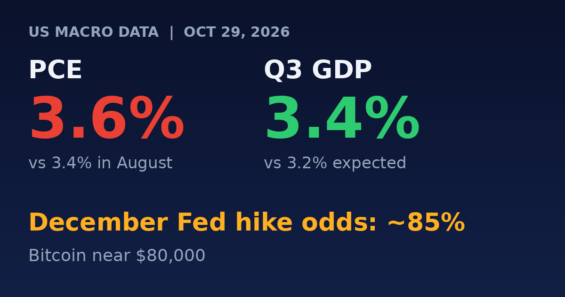
US inflation accelerated in September while the economy grew faster than expected in the third quarter, strengthening the case for another Federal Reserve rate hike in December. The PCE price index rose 0.5% on the month, in line with forecasts, and 3.6% from a year earlier, up from 3.4% in August.
Core PCE, which excludes food and energy, rose 0.3% on the month and 3.1% year over year, after 3.0% in August. Higher gasoline and goods prices drove the acceleration. Consumer spending rose 0.5% in nominal terms in September, but after adjusting for inflation it was flat, which points to a weaker start to the fourth quarter. Over the July to September quarter, spending grew at a 3.8% annualized rate.
The Commerce Department’s advance estimate showed GDP growing at a 3.4% annualized rate in the third quarter, above the 3.2% economists expected.
The data landed a day after the Fed held its rate at 3.75% to 4.00%, with two members voting for a hike. Chair Kevin Warsh said energy prices had moved higher again and that the Fed wants to keep broader price changes from spreading. CME’s FedWatch tool put the chance of a December hike at about 84.6%.
For crypto, strong growth combined with sticky inflation means higher rates for longer. The 10-year Treasury yield briefly rose back above 5% this week, and Bitcoin has slipped to about $80,000, as higher yields make risk assets less attractive.
Track the market yourself with AiTraderView’s FREE tools: Crypto Cockpit for charts and 75+ indicators, Crypto Screener to find setups, and Crypto Portfolio to follow your holdings. Just create a FREE account and try them yourself!
Sources:
- The Standard (Hong Kong): US inflation heats up in September; consumer spending rises
- Investing.com: Bitcoin weakens to $80k as hawkish Fed, mixed tech earnings weigh
⚠️ RISK WARNING & AI DISCLOSURE
- This information is generated by Artificial Intelligence (AI) and complex algorithms. While advanced, these systems can contain errors or inaccuracies and are for educational purposes only.
- Technical analysis provides no guarantees; this information is purely informative.
- All discussed scenarios are hypothetical and do not constitute predictions or expectations.
- Past performance is not an indicator of future results.
- This is not financial advice and is not intended as a call-to-action for the reader.
- No implicit direction is claimed, and no specific behavior of market participants is suggested.