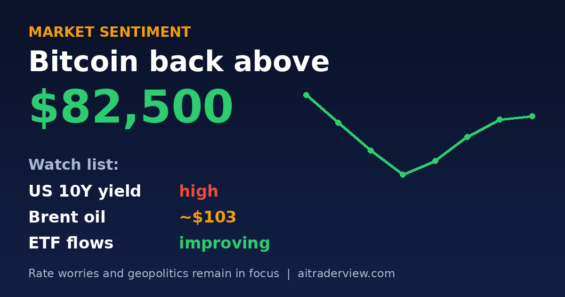
Bitcoin has recovered after a dip earlier this month, but the crypto market remains cautious. High bond yields, expensive energy and uncertainty about Fed policy are still weighing on sentiment.
On Friday, October 9, Bitcoin rose about 0.9% to around $82,475, according to Barron’s, after President Trump said he would carry out no new strikes on Iran before the November 3 midterm elections. Brent crude fell about 1.5% to around $103 a barrel at the same time. According to The Economic Times, Bitcoin traded back above $82,500 on October 10 after a dip below $81,000, helped by improved ETF flows.
The backdrop remains fragile, however. Reuters reported that global money market funds took in about $153.8 billion in a single week, while the US 10-year yield climbed to its highest level since the early 2000s. That points to caution among investors.
Altcoins
SOL could benefit if investors become more willing to take risk. XRP also reacts to legal and institutional news. DOGE and FARTCOIN depend mostly on social media attention and momentum. PUMP, SEI and ARB face token unlocks this week.
Three scenarios
- Positive: lower inflation, falling yields and continued ETF inflows support BTC and altcoins.
- Neutral: inflation meets expectations; BTC trades sideways and altcoins react mainly to their own news.
- Negative: higher inflation, rising rate expectations or new geopolitical tension put the market under pressure, with small altcoins usually falling the hardest.
Key moments this week: CPI (October 14), PPI (October 15), daily ETF flows, the dollar and bond yields.
Sources:
- Barron’s: Bitcoin price and crypto stocks
- Reuters: Global markets flows
- Economic Times: Bitcoin reclaims $82,500
⚠️ RISK WARNING & AI DISCLOSURE
- This information is generated by Artificial Intelligence (AI) and complex algorithms. While advanced, these systems can contain errors or inaccuracies and are for educational purposes only.
- Technical analysis provides no guarantees; this information is purely informative.
- All discussed scenarios are hypothetical and do not constitute predictions or expectations.
- Past performance is not an indicator of future results.
- This is not financial advice and is not intended as a call-to-action for the reader.
- No implicit direction is claimed, and no specific behavior of market participants is suggested.